If you've ever wondered whether your advisor is truly on your side, you and I start in the same place.
Who You'd Be Working With
Why I Walked Out
I spent nearly two decades on the legacy side of the industry. I was relegated to programs and investment strategies that came with layers and layers of fees, and there were no options without those layers. I couldn't remove them, and I didn't believe what my clients got for them was worth it.
My clients were confused by all of it: the fees, the logins, the statements nobody had the time to explain. And what they needed most was real tax planning, which I couldn't give them there.
I chose to become a fee-only fiduciary because I didn't want to be a salesperson. I wanted to do what's actually in your best interest, inside a structure where that's a legal duty, not a slogan.
How I Work
What You Can Expect From Me
I ask for your tax return.
You can't plan around a number nobody has looked at. I look at your return throughout the year, not just when your CPA is filing it, because almost every tax strategy has to be in place before the year ends, not by April 15.
I tell you every fee, out loud.
You'll know your all-in fee before you sign anything. Any change is in writing before it applies.
I put a warranty on my fee.
If you're not completely satisfied with our progress in your first six months, I stop charging you, help you find a new advisor, help with the transfer, and refund the fees from those six months. It covers my advisory fees, not investment results, and the full terms are in the client agreement.
And a line I say to my kids, Noah and Lucia: don't be upset about the results you didn't get from the work you didn't do.
It applies to portfolios more than almost anything else I know. The plan only works if it actually gets implemented, which is why I stay on you about it.
So my clients can fully relax. Not because they stopped paying attention, but because they know exactly what they own, what it costs, and who's watching it.
The best thing anyone gets out of working with me isn't a portfolio. It's the ability to stop running the "are we going to be okay" loop.
That, more than any chart, is the product.
How I Got Here
Three moments that made this firm.
Nearly twenty years in
19 years, 335 days
On track for the twenty-year service wristwatch, and increasingly unable to recommend what I actually believed.
The decision
One month short
I left one month before the twenty-year mark. People ask if I regret it. I don't. All I missed was the wristwatch.
What I built
A fiduciary firm
Fee-only and independent, built so the advice has to be right for you even when it costs me.
Why He Left
I Was Inside It
I want to be precise about my part in this. I didn't set those fees, and they didn't go to me. But I couldn't take them off my clients' accounts, and I couldn't move my clients into a strategy that avoided them.
Early in my career I recommended programs with extra fees attached, in good faith, because I'd been trained to believe there wasn't a better way. That part isn't somebody else's story. So when I tell you the legacy side of the industry substitutes convenient recommendations for correct ones, I'm not reporting a rumor.
I'm confessing.
And that's exactly why I built the practice the way I did. Fee-only, so nobody pays me but you.
Fiduciary, so putting your interests first is a legal obligation and not a slogan. Boutique on purpose, so every client works with the person whose name is on the door.
The Reversal
"Is That the Best I've Got?"
Here's the story I'd want you to know before you trust me with anything. I wrote a book, UnBrainwashed Investing, and much of it was about how to use bonds, or at least how the industry uses them.
Then I reread it, and my honest reaction to my own best argument for bonds was: is that the best I've got? I couldn't defend it to myself.
So I acted on it. I moved essentially my entire client base out of bonds. The book is still out there making the old argument, so I'd rather you hear the update from me.
I couldn't defend it, so I stopped recommending it. That's the job.
The question to carry
If your advisor has never once changed their mind in public, is that because they have never been wrong?
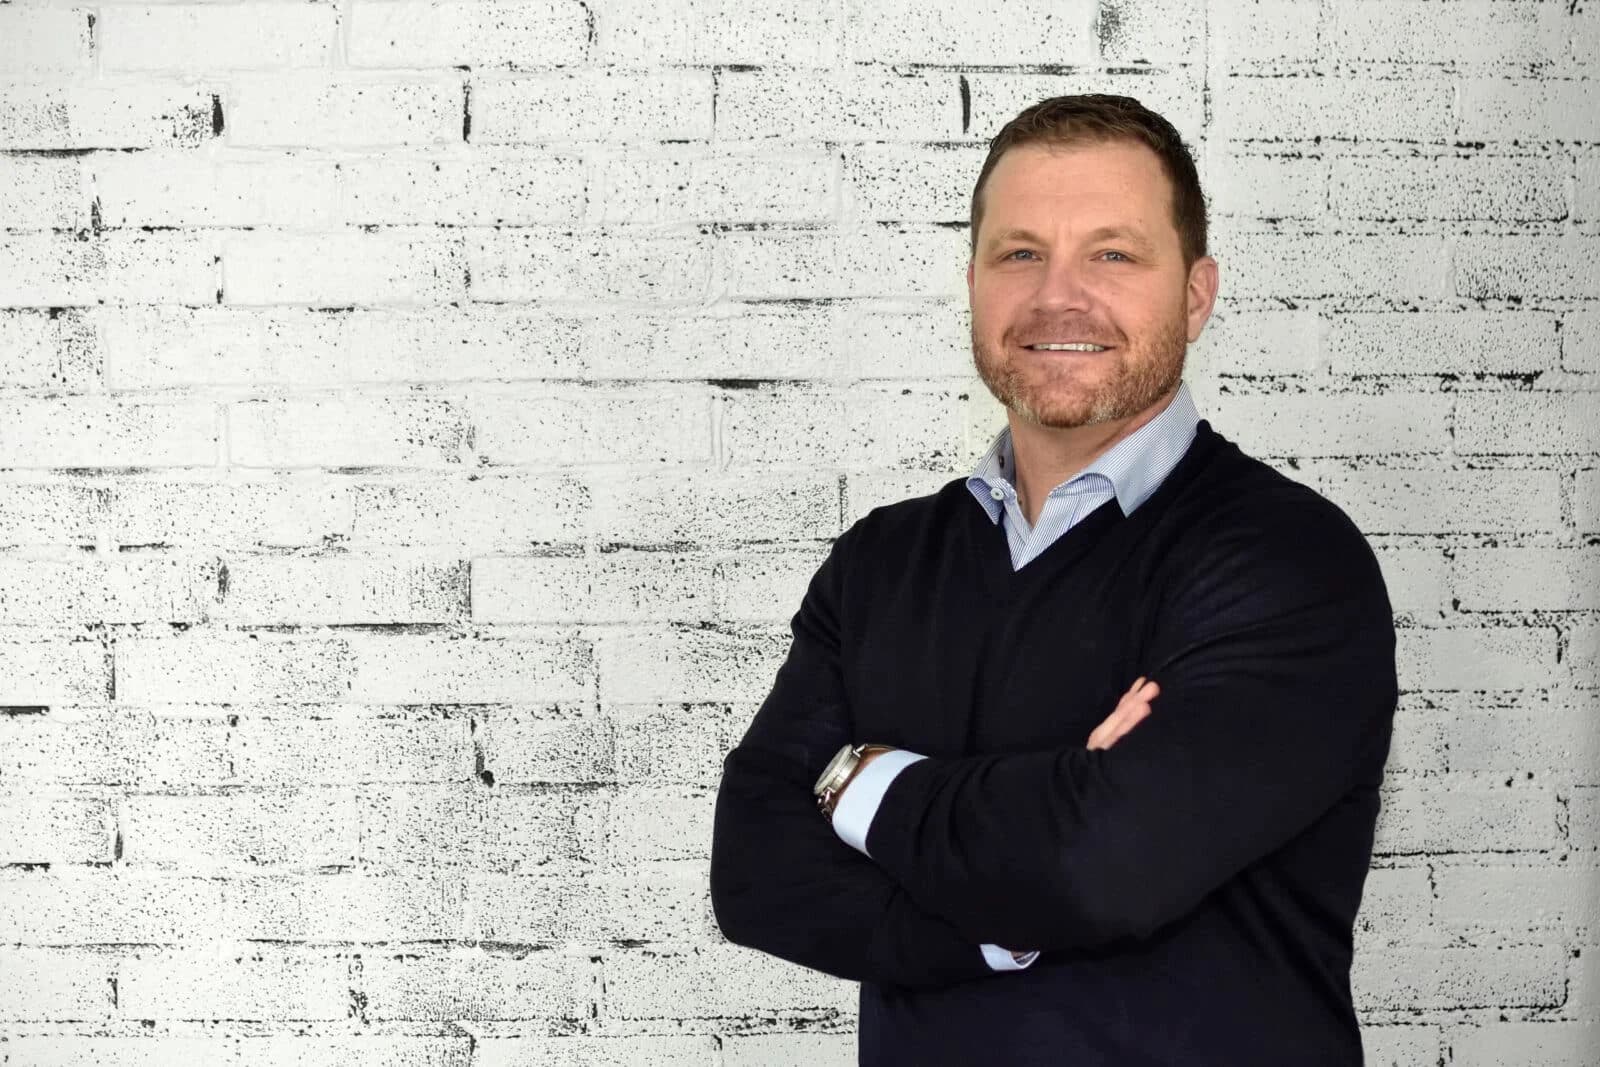
Shaun M. Jones
Questions
The Short Answers
Who is Shaun Jones?
Shaun M. Jones, CFS, CFP®, is the president and founder of Jones Fiduciary Wealth Management. He spent nearly two decades on the legacy side of the industry before leaving to build this firm for the future of advice.
He wrote UnBrainwashed Investing, contributed to Real Life Financial Planning for Physicians, has written for CNBC online, and hosts the Unbrainwashed Success podcast on Apple Podcasts and Spotify.
How are you paid?
Fee-only. You pay me, and no one else does. As a fiduciary I'm legally bound to put your interests first, so there are no commissions and no hidden layers quietly shaping what I recommend.
Who do you work with?
The people who end up on my calendar are usually inside one of three moments: the sale of a business, the sale of a property, or the last day of a career. Each one has a window where the tax strategy matters as much as the portfolio, and usually more.
The Who We Serve page walks through all three.
What makes you different from the advisor I have now?
Three things, and none of them is a promise about returns.
Tax planning comes first. If a sale or a retirement is coming, we plan the tax around it before we build the portfolio, not after.
I read your actual tax return. Not just when your CPA is filing it, but throughout the year, because almost every tax strategy has to be in place before December 31.
And there's a Fee Warranty behind my fee. If you're not completely satisfied with our progress in your first six months, I refund the advisory fees from those months. It covers fees, not investment results, and the full terms are in the client agreement.
Where does your own money go?
I actually invest in the same way I recommend to my clients. The order of operations matters, so here's how that works in my own house. I don't go looking for products to put clients in. I figure out what I want to own, I invest my own money, and then I share what I found with the people I serve. The alignment is a byproduct of my own conviction, not a marketing posture.
Owning what my clients own can look like a conflict of interest, and you should know that up front. It's a fair thing to ask me about.
What does it cost to talk to you?
Nothing. The first step is a Curiosity Call: bring the question that has been sitting in the back of your head. There's no charge, and there's nothing to sign.
On the Record
The latest from the Resource Center.
Talk to Me
Schedule a Curiosity Call, and bring the question that has been sitting in the back of your head. There's no charge, and there's nothing to sign.
Or read exactly what working together looks like first: Walk Through the Process
There's also a Fee Warranty behind all of it. Read how the Fee Warranty works